Any treasury. Any phone.

Payment infrastructure for institutions: from treasury to a basic phone, with or without a bank account.

Beyond the border and the counter.

The wallet reaches the phone. The money does not reach the wallet.

  • Reach

    The money stops before the person.

    No account, no smartphone, no way in: accounts and apps end before the people an institution most needs to pay.*

  • Cost and speed

    Money from abroad is slow and expensive.

    A transfer into the Levant costs 7 to 11 percent and takes days, and a supplier's invoice passes through two or three banks and arrives short.*

  • Control

    No one holds a single record of the payment.

    The list, the approval, the transfer and the receipt sit in four systems; a shared ledger records each payment once, and every party reads the same record.*

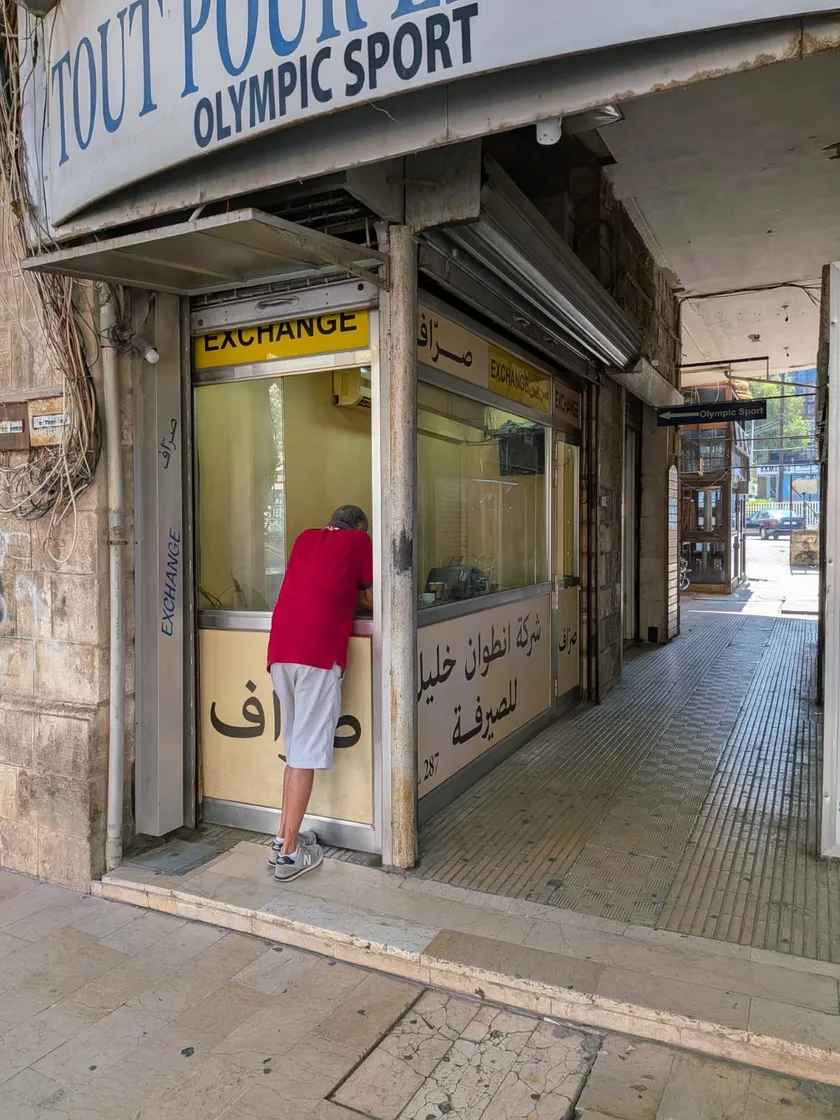
A customer at an exchange house counter, Lebanon, 2026
Exchange house, Lebanon, 2026.

The money exists. The wallets exist. Saleem connects them.

Money in. Money out.

Licensed partners receive, convert, hold and pay out. Saleem validates instructions, screens parties, routes payments, records each step and returns the reconciliation file.

  1. approvesInstitutionTwo people approve the payment run before anything moves.
  2. receives and convertsLicensed money-in partnerThe institution pays in its own currency; the partner converts it to regulated digital money.
  3. validates, screens, routes, recordsSaleem platformEvery party is checked, the route is chosen, and every step is recorded.
  4. holdsRecipient wallet or accountPaid into the wallet the recipient already has, or held safely for them under their phone number.
  5. pays outLicensed payout partnerSpend at a merchant, or cash out at a licensed exchange house or bank.

Access channels: USSD and SIM Toolkit, feature-phone app, Android and iOS, the institution's console.

Built and demo-ready, pre-launch. Live transactions follow licensed partners on both ends.

  • A wallet held for the recipient. A keypad in their hand.
  • Same wallet, same number, whatever phone comes next.
  • Recipient balances are to be held by a licensed custodian and accessed through Saleem's interfaces; keys do not sit on the handset. This is the target operating model at launch. Every party checked; every payment recorded.
  • The exchange rate is set by the licensed partner, not by Saleem.
*XXX# Call
SALEEM
  1. 1 Balance
  2. 2 Send
  3. 3 Receive
  4. 4 Cash out
Reply
Saleem Enter PIN OK
Saleem Confirm transfer? OK
Settled in seconds

USSD on a basic phone

Reach. Control. Connect.

Reach

Any wallet or account already there. Ours where none is.

Amal in Homs receives cash assistance on the phone she has. No app, no account, no queue.

Control

One record, treasury to recipient. Two people approve. Books balance the same day.

Connect

Plugs into the wallets, banks and networks already in the market; your brand, your rules.

Supported in demo build

  • Stellar
  • ADI Chain
  • Solana
  • Polygon PoS
  • USDC · USD
  • USDT · USD

Marks shown are the property of their respective owners and indicate technical support, not endorsement. All twelve networks and tokens

What moving money costs today.

MoneyPeople
The world$685 billion a year sent home to low and middle income countries (World Bank)593 million people use a mobile money wallet every month (GSMA)

Why they need paying Aid · Wages · Remittances · Suppliers

World Bank; GSMA State of the Industry Report on Mobile Money 2026; Saleem estimates marked with an asterisk.

Cash costs 17 cents on the dollar, and the record.

$1.1 billion a year

Delivering $6.6 billion of humanitarian cash at 17 cents on the dollar (WFP, CALP, 2024).*

$0.7 to 1.0 billion a year

If delivery cost what one digital programme achieved, 1.4 to 6.7 cents (Afghanistan, 2023).*

$20 billion a year

Fees above the 3 percent target on money sent home worldwide (UN).

With Saleem Reported in your measures: cost per dollar, time to recipient, first-time success, a record per payment, money lost, phones reached. Every pilot prints the numbers.

CALP and ALNAP 2025; WFP 2023 via Aiken et al.; Aiken, Blumenstock et al. 2023; United Nations. Derived figures marked with an asterisk. What cash costs, in full

Money that follows the rules you set.

Payments can be timed, conditional, held until both sides agree, or paid in instalments. Every rule leaves a record.

Designed, pre-launch. Financing comes from a licensed partner; Saleem schedules it and records it.

Built. Ready to demo.

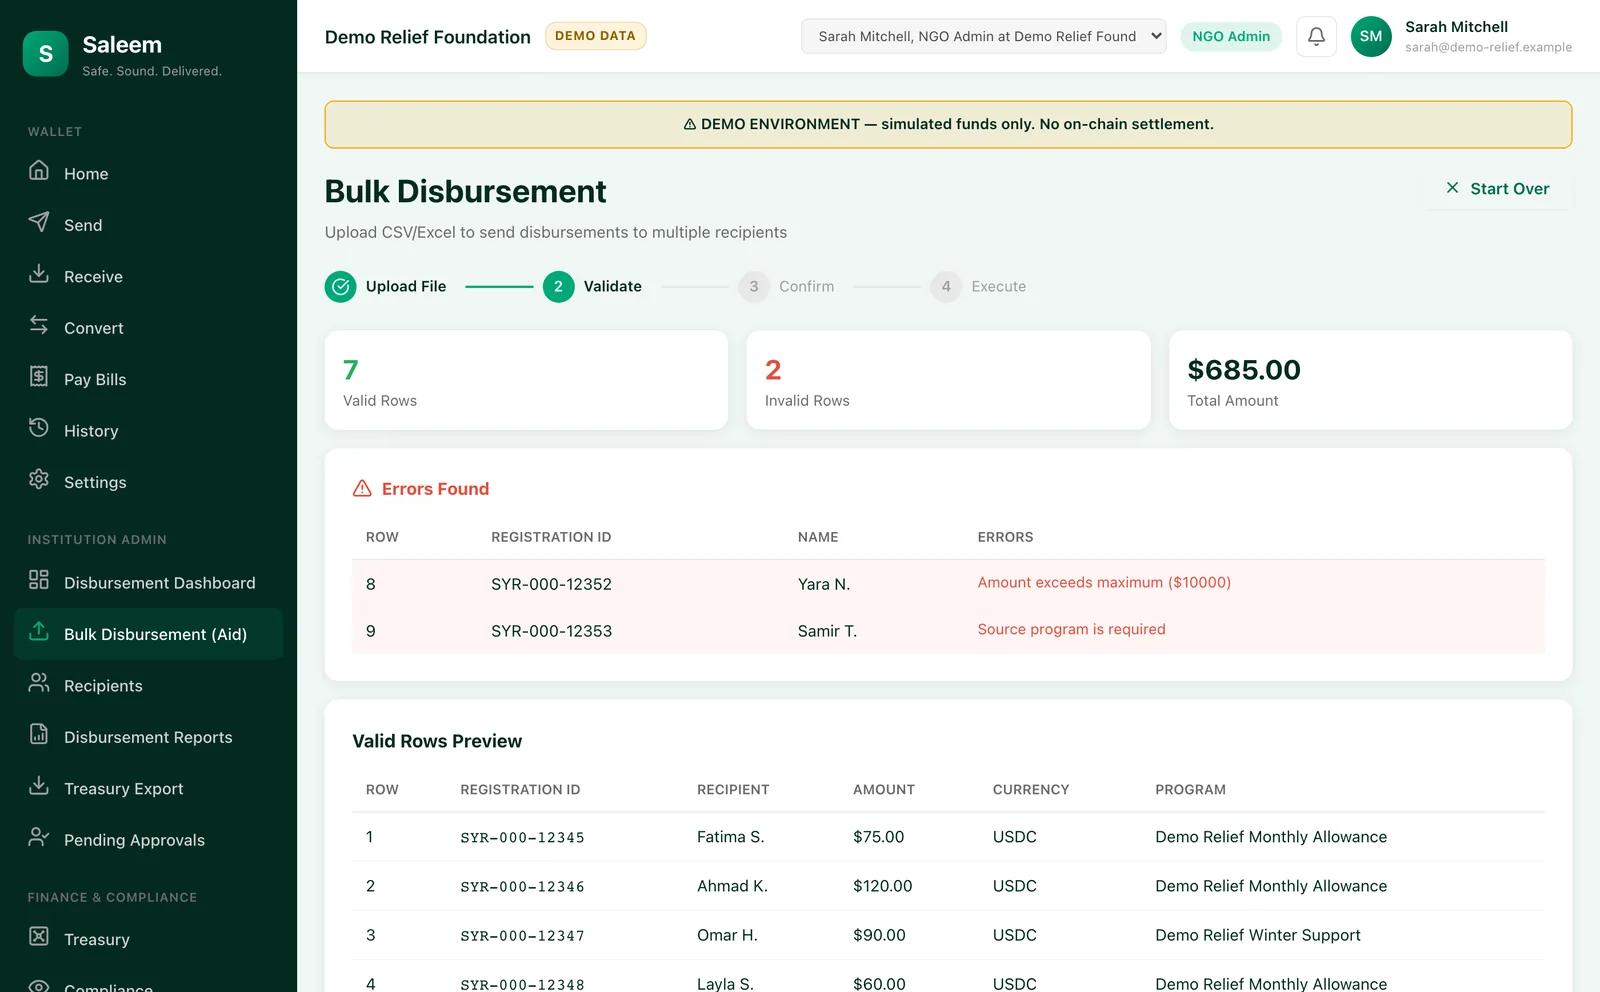
Saleem desktop console: bulk disbursement file validation, every row checked before a second person approves
Send
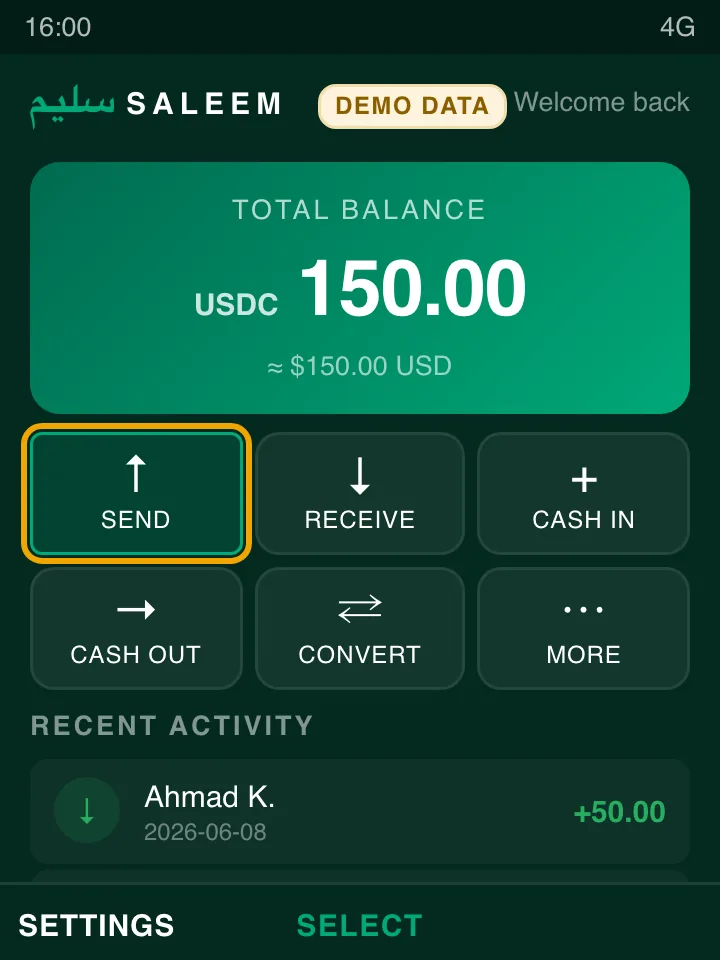
Saleem KaiOS home screen showing the USDC 150.00 balance, demo data
Receive
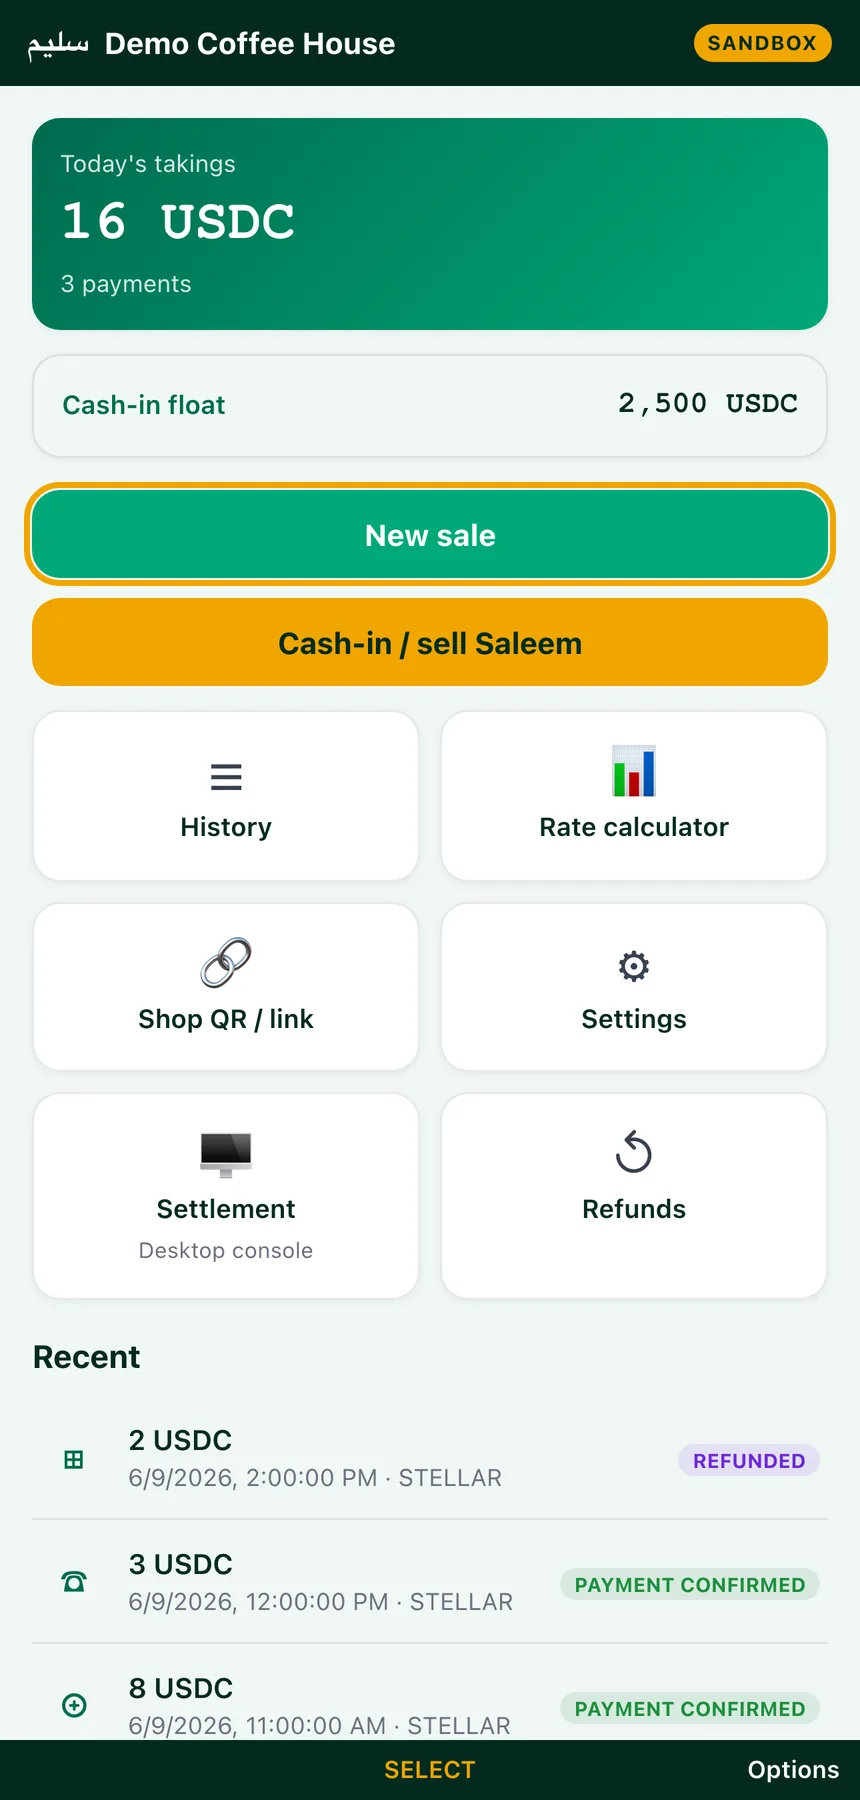
Saleem merchant POS home screen on a phone: takings, new sale, cash-in, refunds
Spend

Six client surfaces are built and demonstrable against mocked services. The production backend, licensed-partner connections and independent security testing remain pre-launch work.

Platform walkthrough, demonstration environment

Where the rails stop.

Domestic systems stop at the border. Bank transfers stop at the bank. Aid platforms stop at the local partner. Saleem is built to run the full length, from any treasury to the phone in hand.

  1. Treasury
  2. Bank transfers stop at the account or the correspondent
  3. Aid settlement layers stop at the local partner
  4. Remittance operators stop at the payout counter
  5. Mobile money stops at the operator boundary
  6. App-first providers stop at the smartphone
  7. Phone in hand

Saleem

The conditions are in place.

World Bank Global Findex 2025. GSMA, State of Mobile Internet Connectivity 2025, and Chainalysis, 2025 Global Crypto Adoption Index and Sub-Saharan Africa excerpt. Pakistan Virtual Assets Act 2026; Nigeria ISA 2025; Kenya VASP Act 2025; Jordan Virtual Assets Law 14 of 2025. Syria electronic payments framework, August 2026: secondary reporting, stated with its status on the evidence page. See the evidence

  1. Any route two licensed institutions want to open. The first: the Levant and Pakistan, from the Gulf.
  2. First corridors in preparation: the Levant and Pakistan from the Gulf.
  3. Registered in ADGM; Stellar x CV Labs Accelerator, cohort 2026.
  • CV Labs
  • Stellar

Marks shown indicate registration or programme participation, not endorsement, and are the property of their respective owners.

Watch the cohort showcase, 47:50

Founded by Ramy Soliman and Faris Sibai. Meet the founders
Who runs money across it.

Distribution and payout partners

They carry the last mile; they keep the customer at the counter.

Institutions pay.

The phone is in hand. The wallet is already there. Saleem brings better money to both.

Talk to the team

sales@saleem.digital www.saleem.digital

Exchange house, Lebanon, 2026.